ARB Apex Bank

Advancing financial inclusion with a centralized banking platform

Accra, Ghana,

Post Meta

At a Glance

  • Deployed Temenos Inclusive Banking, a purpose-built solution based on Temenos Core, tailored to the needs of inclusive financial institutions
  • Centralized all 147 member banks onto a single Temenos platform, achieved in 18 months with each bank migration completed in approximately three weeks
  • Agency banking via fintech partners enabled with Temenos open APIs
  • Between 1-2 million transactions processed per month
  • Centralized regulatory reporting now enables timely submission of returns to the central bank, reducing the risk of penalties

The case for centralization

ARB Apex Bank is the oversight body for rural and community banks in Ghana, providing governance, shared services, and technology infrastructure to a network of 147 member institutions. Its mandate is to serve communities that commercial banks do not reach, and in doing so support the financial inclusion agenda that underpins Ghana’s economic development strategy.

ARB Apex Bank’s member institutions had operated in a highly fragmented technology landscape. Each bank managed its own systems independently, using a mix of legacy platforms and manual processes. That created inefficiencies and risks.

Regulatory reporting required manual data collection from across the network, a slow and error-prone process. There was no common infrastructure through which digital services could be developed and offered to customers. That made it harder to compete with the digital capabilities of commercial banks and ultimately deliver on its core mission of extending financial services to underserved communities.

Centralization addressed all these challenges at once. By bringing every member bank onto a single platform hosted at ARB Apex Bank headquarters, the network could standardize operations, consolidate reporting, and build the shared digital infrastructure needed to scale.

Standardizing to scale

In 2004 ARB Apex Bank deployed Temenos Inclusive Banking, a purpose-built solution based on Temenos Core, tailored to the needs of inclusive finance institutions

Rather than requiring implementation at each bank, Temenos Inclusive Banking established a standardized configuration for core requirements while retaining the flexibility to accommodate local variations. The result was a deployment model that could be replicated consistently and efficiently across the entire network.

Each bank migration took approximately three weeks, and over 18 months the full network was brought onto the platform. It enabled ARB Apex Bank to gain a single view of operations across all member banks for the first time.

Going the extra mile

Any program of this scale and complexity will encounter moments that test a partnership. When ARB Apex Bank experienced performance pressures during the implementation, with batch processing running longer than expected and creating operational strain across the network, the response from Temenos was immediate.

The Expert Services team engaged directly, working alongside the bank to diagnose the issue and optimize the system. Processing times were brought down substantially as a result.

For ARB Apex Bank, that moment was as much a proof point as any feature or capability. What defines the Temenos relationship, in their view, is not simply what the platform can do, but also the readiness of the team behind it to engage, listen, and find solutions. Across more than two decades, that consistency of support has been as important to the partnership as the technology itself.

Temenos is always prepared to go the extra mile. Whenever we are in difficulty and we reach out, they sit down with us and find solutions. That’s what ultimately builds an enduring partnership.”

Godwin Amarsey Ofoe, Head, Business Applications Unit, ARB Apex Bank

Opening new channels, growing deposits

With all member banks on a common platform, ARB Apex Bank was able to connect its network to the wider digital financial services ecosystem. Through Temenos’ open APIs, the bank integrated with fintech partners to enable agency banking, making it easier for the most remote customers to make deposits and access essential financial services.

The impact on deposit volumes has been significant. The network now processes between one and two million transactions per month, a scale that was not achievable before the digital transformation. The competitive dynamic with large commercial banks has shifted.

With the introduction of digital channel services, the banks can retain customers and increase their presence in rural areas. We are now positioned as a network driving the financial inclusion agenda and contributing to the growth of the economy.”

George Edward Neizer, Head, ICT Department, ARB Apex Bank

Faster and more reliable reporting

One of the less visible benefits of centralization has been the transformation of regulatory reporting. Before all member banks were connected to a single platform, consolidating data for submission to the central bank was a slow and unreliable process. Late or incomplete submissions carried the risk of penalties, a risk that fell on individual member banks that were often ill-equipped to absorb it.

With the network centralized on Temenos, data is now available in consolidated form and can be extracted quickly. Submissions are made on time, and the compliance risk associated with fragmented reporting is significantly reduced.

Building the future of financial inclusion

With a unified platform serving 147 member banks, ARB Apex Bank has created a foundation not only for today’s operations but also for tomorrow’s innovations. The bank is already leveraging Temenos Financial Crime Mitigation across the network and is exploring how AI can further strengthen their compliance and anti-money laundering operational efficiency.

More importantly, the centralized platform gives the network the agility to continue expanding financial services to underserved communities across Ghana. For ARB Apex Bank, technology is not an end, it is an enabler of its mission to bring accessible banking services to the people who need them most.

Having seen first-hand the direction Temenos is taking, especially with AI, we’re as confident in the partnership as we were more than two decades ago. Every improvement, every new innovation helps us further our mission to reach more people with financial services.”

Godwin Amarsey Ofoe, Head, Business Applications Unit, ARB Apex Bank
Contact us

Related Success Stories

  • ASA International – Success Story

    ASA International is one of the world’s largest international microfinance institutions. It provides small, socially responsible loans to low-income entrepreneurs, most of whom are women,…

    ASA International - Success Story
  • LOLC Cambodia – Success Story

    LOLC Cambodia is one of the country’s largest and most mission-driven microfinance deposit-taking institutions (MDIs).

  • VisionFund International – Success Story

    VisionFund International is a subsidiary of World Vision International. Established in 2003, its mission is to support children from economically disadvantaged communities by empowering families…

    VisionFund International - Temenos Success Story

LOLC Cambodia

Modernizing to expand financial inclusion

Phnom Penh, Cambodia

LOLC Cambodia - Success Story

Post Meta

At a Glance

  • Leading microfinance institution serving over 330,000 customers across Cambodia
  • Temenos Financial Inclusion deployed in 2017 to support digitization and expand inclusion
  • Upgrade to R22 in 2024.
  • 57% customer growth since 2017, supported by a scalable and future-ready core banking system
  • Expanded General Loan Portfolio (GLP) by 308% and almost halved its cost to GLP ratio to 4.31%
  • Operational efficiency gains, including reduced manual processes and enhanced reporting capabilities
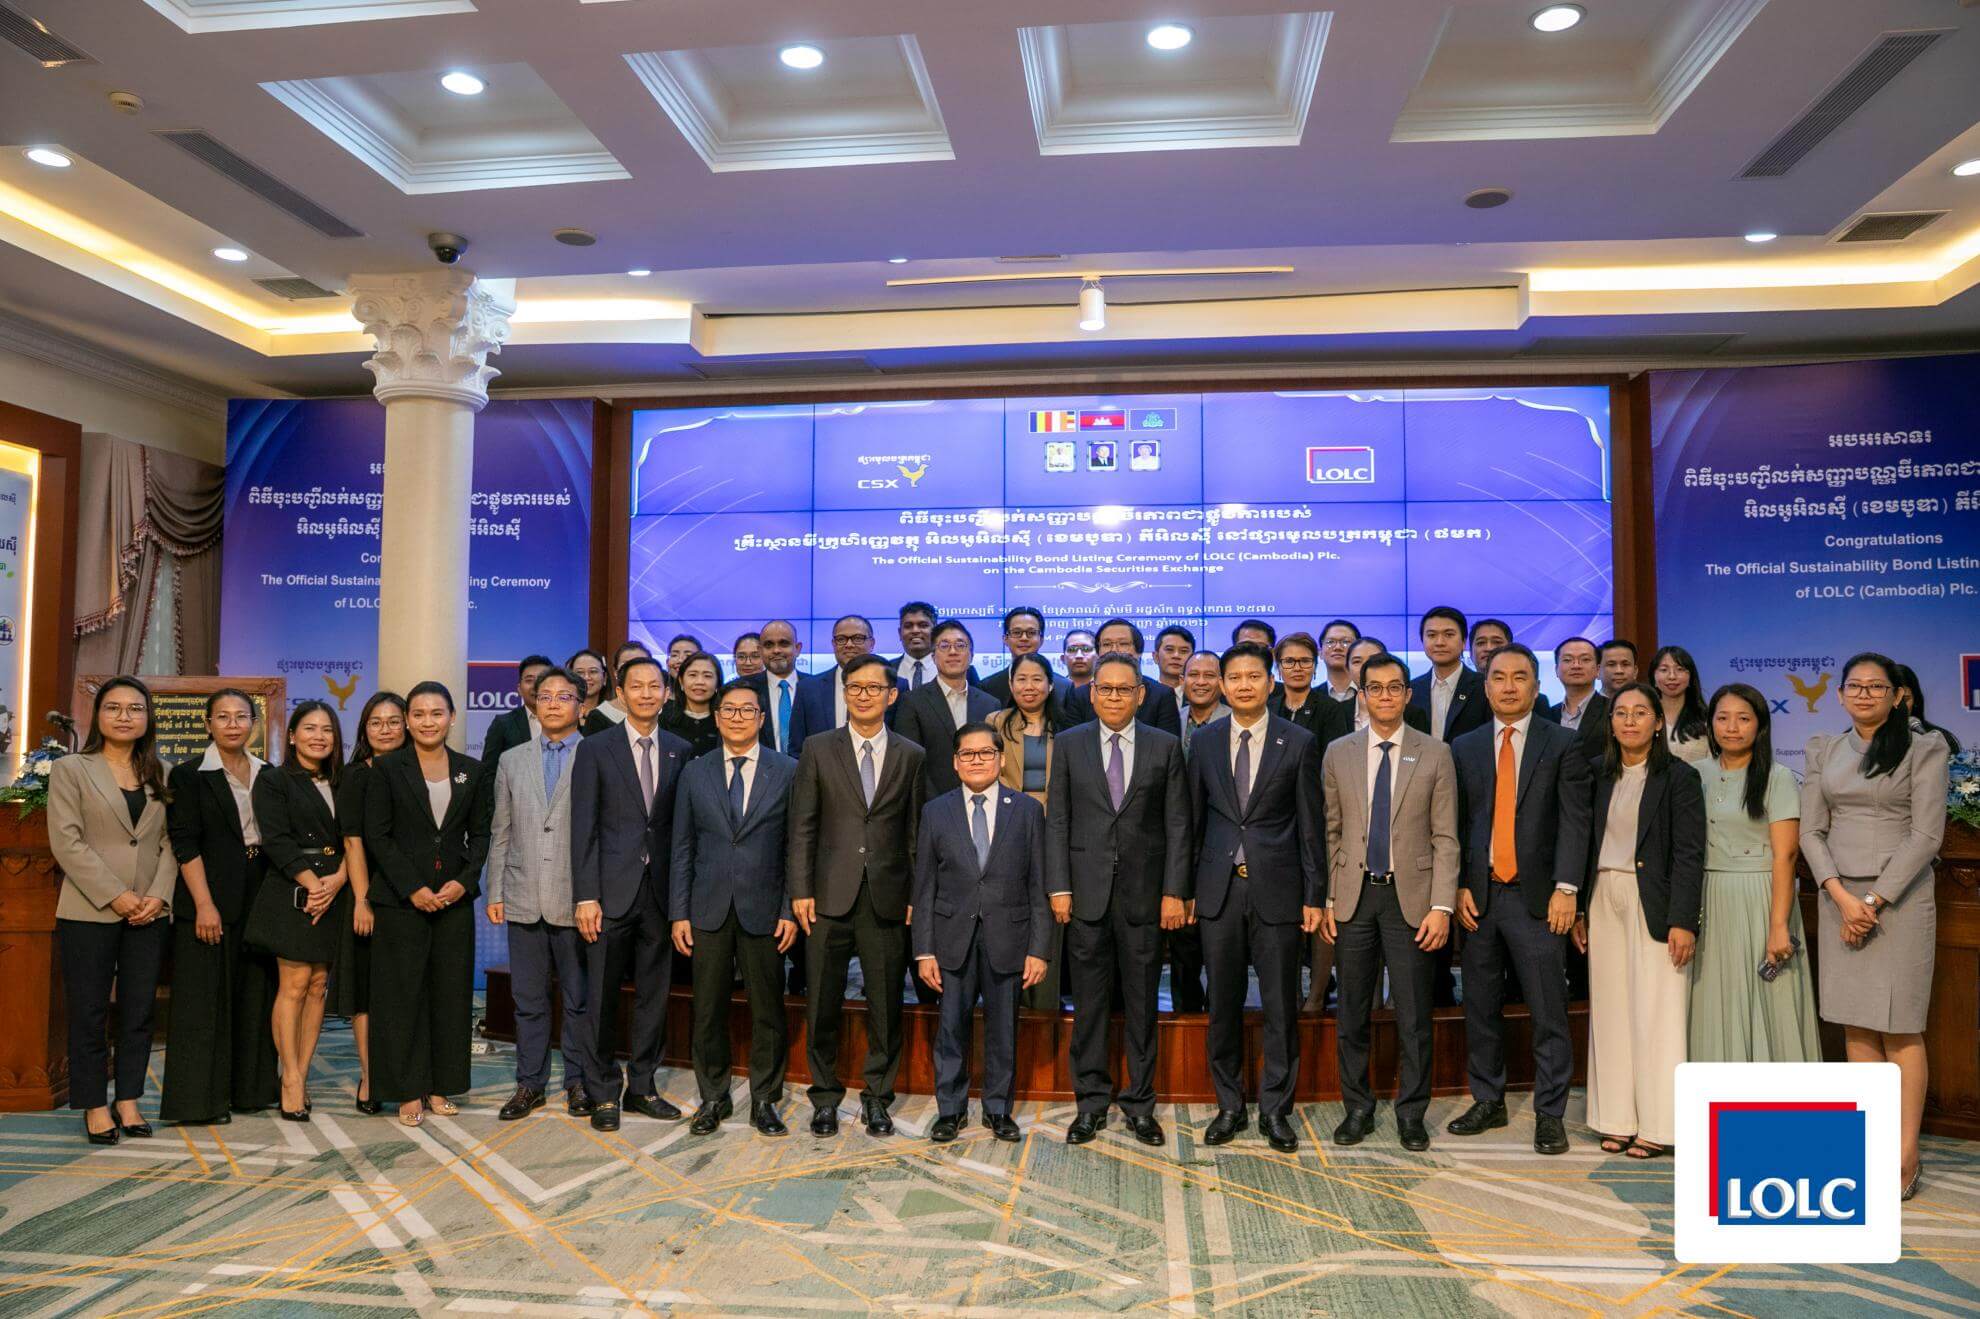
Bond Listing Ceremony Of LOLC (Cambodia)

LOLC Cambodia is one of the country’s largest and most mission-driven microfinance deposit-taking institutions (MDIs). With a strong focus on rural communities, the institution provides a range of financial services aimed at empowering underserved populations. Alongside loans, it also offers deposits, a mobile banking application, ATM cards, and local fund transfer services. Since its founding in 1994, LOLC Cambodia has grown to serve over 330,000 customers, with loan assets exceeding $1.5 billion and customer deposits surpassing $1 billion. LOLC is nationally ranked first for number of borrowers and second for loan portfolio and deposit balance. It employs 3,700 people.

Despite this scale, LOLC’s mission remains elegantly simple.

Our goal is to provide financial services to those who need them most, with speed and convenience.”

Mr. Sok Sophal, CFO/DCEO, LOLC Cambodia

To this end, it has maintained a focus on the low end of the market, with 79% of its clients based in rural areas, and 60% of its loan book made up of group loans and micro loans.

The case for change

Prior to 2017, LOLC was hampered in a number of ways. The legacy core banking system had to be deployed as separate environments in each branch, resulting in significant technical support to maintain them and enable new branch openings. For example, database backups were carried out in individual branches and sent to HO for consolidation, while data was manually written from CD/DVD to tape drive for retention. Product updates required hard coding or SQL server scripting. There was an over-reliance on third-party applications to support some core processes, such as updating loan repayment schedules with EIR (Effective Interest Rate) and generating key reports such as the Customer Poverty Index. Also, individual databases were needed for each currency.

These inefficiencies filtered through to the customer experience. Manual onboarding processes made it difficult for new customers—especially in rural areas—to access financial services quickly. The outdated core banking system lacked flexibility and automation, limiting LOLC’s ability to scale. Regulatory requirements, including IFRS compliance, demanded a more robust reporting and risk management framework. At the same time, a rapidly evolving digital landscape was opening up new opportunities to integrate with mobile banking and real-time payments—such as Cambodia’s Bakong platform—which LOLC was not equipped to take advantage of.

Aligning strategy with solution

In 2017, LOLC implemented Temenos Financial Inclusion as the foundation for its modernization strategy. The decision to select Temenos initially rested on three essential attributes, recalls Sophal

First, cost efficiency. Temenos was shown to offer significant savings over time due to lower maintenance costs and the reduced need for expensive customizations. The standardized configurations and open architecture also contribute to a lower TCO. Moreover, ease of scalability has ensured that costs remain predictable and manageable as the bank expands.

Industry leadership was a second factor.

Temenos has a long-standing reputation in the banking industry, with extensive experience in delivering core banking solutions to a wide range of financial institutions.”

Mr. Sok Sophal, CFO/DCEO, LOLC Cambodia

Finally, LOLC was impressed by the pool of leading technology and consulting firms, certified professionals, and partners in the Temenos ecosystem. These alliances bring additional domain expertise, product innovation, and know-how of successful implementations, giving LOLC peace of mind that modernization could be sustained.

Alongside these strategic pillars were specific capabilities of Temenos Financial Inclusion that marked it out. These included automation and STP to increase operational efficiency; integration with digital banking, CRM, and regulatory platforms; real-time and cross-border transaction processing; multi-branch and multi-country flexibility; the availability of the Product Builder (Wizard) and the ability to originate loans from all channels.

Summarizing its decision, Sophal says, “We selected Temenos Financial Inclusion for long-term scalability, automation, digital transformation, and inclusivity.”

Building on success

In 2024, LOLC completed the upgrade to R22. The update included, among others, migration from TAFC to TAFJ; new hardware, databases, and OS; integration with multiple third-party systems and devices; and the implementation of 12 new modules.

The technical complexity of the upgrade was coupled with stakeholder challenges, explains Duleep Liyanage, CIO. “Colleagues had become very familiar with the R14 version and were resistant to change. We were very conscious about bringing all users with us, so training and communication were a priority.”

The move to R22 was managed by Temenos Upgrade Services (TUS). “They brought a very holistic and systematic approach to the project,” recalls Duleep

They implemented a robust governance structure, established clear communication channels, conducted extensive testing, and applied operational know-how, such as setting optimal data migration volume levels.”

Duleep Liyanage, CIO, LOLC Cambodia

Duleep adds that TUS was also highly aware of the importance of stakeholder engagement, with user feedback sessions, incentives and rewards, and milestone celebrations forming a key part of the upgrade project.

Modernization in action

The solution has delivered on its promises. From 2017 to 2024, LOLC expanded its General Loan Portfolio (GLP) by 308%, saw customer numbers grow by 57%, and almost halved its cost to GLP ratio to 4.31%.

Behind these numbers is a modern customer experience. Users are able to open accounts and access services in a fraction of the time and select from a range of highly personalized products. New offers are continually developed and deployed, increasing choice. Digital transactions include integration with Cambodia’s Bakong real-time payment platform to allow instant fund transfers across mobile. Advanced fraud detection, encryption, and real-time monitoring have improved security and trust. And the adoption of IFRS 9 accounting standards has enhanced LOLC’s ability to monitor non-performing loans and manage credit risks effectively.

Tangible impact

Growth numbers alone don’t tell the whole story. “Temenos Financial Inclusion has had a tangible impact on the lives of its customers,” says Sophal. Faster access to loans has helped small businesses and farmers secure funding without long delays. New loan products for women entrepreneurs and small businesses are increasing inclusion and boosting entrepreneurship in the country. Mobile banking adoption has surged, enabling customers in remote areas to manage accounts, send payments, and receive funds without visiting a branch. And simplified deposit services now allow families to save for their future more effectively.

For many of our customers, digital banking is their first experience with formal financial services. Temenos has made it possible for us to bridge that gap and provide them with safe, reliable banking.”

Duleep Liyanage, CIO, LOLC Cambodia

Leading from the front

With Temenos Financial Inclusion firmly in place, LOLC is looking ahead. Plans are underway to expand digital lending services, enabling even more customers to access credit with minimal paperwork. LOLC is also working to enhance real-time analytics, using AI-powered insights to better understand customer needs, and explore new financial products such as insurance and investment solutions tailored for Cambodia’s microfinance market.

“With Temenos, we are not just keeping up with change—we are driving it. We are building the future of financial inclusion in Cambodia,” says Duleep.

By adopting Temenos Financial Inclusion, LOLC has positioned itself as a leader in inclusive banking, ensuring that more Cambodians—especially those in rural areas—have access to modern financial services. With improved customer experiences, faster onboarding, and a scalable platform for future growth, LOLC is setting new benchmarks in the microfinance industry.

That elevates its relationship with Temenos well beyond a client/vendor, explains Duleep. “Temenos is more than a technology provider; it is a partner in our mission to bring financial services to those who need them most and an indispensable part of our success story.”

Related Success Stories

  • ASA International – Success Story

    ASA International is one of the world’s largest international microfinance institutions. It provides small, socially responsible loans to low-income entrepreneurs, most of whom are women,…

    ASA International - Success Story
  • CreditAccess Grameen – Success Story

    CreditAccess Grameen is India’s largest microfinance institution. It has 4.9m customers and manages assets of over $3.2bn. It employs 19,400 people across nearly 2,000 branches…

    CreditAccess Grameen - Success Story
  • VisionFund International – Success Story

    VisionFund International is a subsidiary of World Vision International. Established in 2003, its mission is to support children from economically disadvantaged communities by empowering families…

    VisionFund International - Temenos Success Story

VisionFund International

Upgrading and scaling to better serve entrepreneurs

California, United States

VisionFund International - Temenos Success Story

Post Meta

At a Glance

  • Running Temenos Financial Inclusion successfully for 23 years!
  • Increased efficiency by 40%
  • Reduced customer onboarding time from three days to an hour
  • 61% faster to process loan applications

VisionFund International is a subsidiary of World Vision International. Established in 2003, its mission is to support children from economically disadvantaged communities by empowering families through microfinancing for entrepreneurial ventures. As well as loans, it also offers savings and insurance products. It operates 28 microfinancing institutions around the world, 576 branches (with the majority in Africa), and employs over 7,000 staff. To date, it has made over one-million loans totalling $706m, with 69% made to women.

Customer-centric innovation

Vision Fund’s mission goes hand-in-hand with an appetite for innovation. “Innovation is really about being customer-centric. We can’t deliver our goals without embracing new ideas and technologies. This is how we bring about the efficiency gains and improvements to business operations that impact the families we serve,” explains the Spokesperson.

For most of its 25 years, this technology to service the unbanked sector has come from Temenos.

Temenos Financial Inclusion is a great solution because it is dedicated to microfinance institutions, and comes with many preconfigured capabilities that are distinct from traditional banking. So we can easily adapt to opportunities, which ultimately enables scalability.”

Spokesperson, VisionFund

Digital efficiencies

For VisionFund, that has meant expanding from its core lending business to adding deposits and insurance products. “The composable architecture of the platform makes it easy to add new capabilities and to deliver these to customers through digital channels. For example, in Uganda we rolled out a ‘Last Mile Mobile Solution’ that allows loan officers to collect data while they are in the field, enabling them to onboard new customers much faster. We’ve cut that from three days to just an hour.”

This digitization has allowed VisionFund to increase efficiency by 40%, by becoming paperless which both lowers cost and drives sustainability, a core KPI. Loan applications have also benefited, and are now completed 61% faster. Management oversight has also improved as a result. “In the past, branch managers and regional managers had no visibility on field work until they received paper reports from the loan officers. Now they can see what is happening with customer registrations and loan applications in real-time.”

Ultimately, this means happier customers, says the Spokesperson.

Customers are more satisfied because they are able to get their loans quickly, and that means loyalty and retention is improving.”

Spokesperson, VisionFund

The platform’s breadth of capabilities and efficiencies are complemented with robust security credentials. “The security features that come with Temenos are at a high level. The database is robust, it’s so difficult to crack that system. And therefore it just gives you the comfort and confidence that you really look for when you’re thinking about your growth strategy.”

Always upgrading

Over the years, VisionFund has regularly upgraded its Temenos core. That exercise has become much faster, explains the Spokesperson. “In 2021 we upgraded the platform in Kenya. It took less than a year, whereas in the past, it could take 18 months.” Ghana, Tanzania, and Zambia are next in line, with go-live due in August 2024. The platform will be configured for each market, a practice that VisionFund has employed from the start. “Customizability is a key feature of the platform for us”.

Key to this speed is the implementation partners that VisionFund has access through Temenos – SG NewTech for the Kenyan upgrade, and Straj for Ghana, Tanzania, and Zambia.

The partnerships that Temenos has are really credible. They really understand the systems and have strong good project management skills, and that makes implementation much faster.”

Spokesperson, VisionFund

The upgrades have also boosted reliability. Today, the Temenos platform is 100% reliable. “It’s available 24/7 to our customers and there are no interruptions at peak times, such as end of the day closing. That gives us confidence that we have the scale to develop and run new offers, such as ATMs.”

Holistic change

For the Spokesperson, selecting a Temenos certified partner should be a priority for any implementation project. Change management is also key. “Change is not easy, and there will always be resistance. Gain confidence at the highest level of your organization. Once you have that in place, it trickles down very easily.”

They also advise avoiding a go-live date at the end of a financial year or key reporting time. “Go live at the end of the month. So if things don’t go according to plan, you have time to remedy them before your key reporting periods. These are the little things that, through our implementations, we have learned along the way.”

The listening partner

VisionFund will be applying these lessons as it continues to upgrade the platform in other countries, as well as adding AI capabilities and Data analytics. It represents the next chapter in a partnership that goes back 23 years and a story with scalability at its heart.

Over 23 years Temenos has proved to be a robust system that can grow with your strategy. It can take you to where you want to be. You can start as a small microfinance business, but then move into trade financing, treasury, and other banking areas. There are no limitations to what it can do.”

Spokesperson, VisionFund

This track record with Temenos points to a successful future for VisionFund, and not simply because of the technology. “Temenos is a very listening partner. They take time to understand our business, ideas and concerns, and are always available. We’ve come a long way with Temenos, and the journey continues.”

Contact us

Related Success Stories

  • LOLC Cambodia – Success Story

    LOLC Cambodia is one of the country’s largest and most mission-driven microfinance deposit-taking institutions (MDIs).

  • ASA International – Success Story

    ASA International is one of the world’s largest international microfinance institutions. It provides small, socially responsible loans to low-income entrepreneurs, most of whom are women,…

    ASA International - Success Story
  • CreditAccess Grameen – Success Story

    CreditAccess Grameen is India’s largest microfinance institution. It has 4.9m customers and manages assets of over $3.2bn. It employs 19,400 people across nearly 2,000 branches…

    CreditAccess Grameen - Success Story

ASA International

From microfinance to full-service banking

Amsterdam, The Netherlands

ASA International - Success Story

Post Meta

At a Glance

•  Deploying core banking platform in 13 countries

• Handles 1,000 concurrent users on the system every day

• Over 3,000 disbursements per day

• Flexibility to deploy on-premise or in the cloud, depending on each country’s regulators

ASA International is one of the world’s largest international microfinance institutions. It provides small, socially responsible loans to low-income entrepreneurs, most of whom are women, across Asia and Africa. Headquartered in Amsterdam and Dhaka, it has 2.3 million clients across 13 countries and employs 13,400 people. It has an outstanding loan portfolio of $369.2 million.

For Rob Keijsers, the company’s Chief Digital and Information Officer, success is the ability to constantly adapt to uncertain markets. “We operate in countries that are more susceptible to geopolitical risks and where credit rules vary and change.” The goal, he says, is to bring stability to these markets by reducing the number of unbanked and underbanked people. “There’s a big market to win in the next couple of years.”

Bringing modern to the masses

To achieve that goal, ASA International has turned to Temenos, deploying its core banking platform across all markets. Along with an in-house built front-end app, the aim is “to give people at the bottom of the pyramid the same, modern phone banking experience that is typical in developed countries.”

Deployed first in Pakistan in February 2024, the Temenos core replaces a bespoke loan system that the business developed in-house 15 years ago. Rob explains that the upgrade to Temenos reflects the importance of having cutting-edge technology. “To achieve a world-class digital experience, you can’t simply put an API layer on top of an old system. We needed a modular, open-architecture system to run our API on top of.”

Part of the issue was scope. “Our loan management system was just that—it only did loans. We wanted a full-blown core banking system, so that we can offer bank-like services and experiences. Temenos core allows us to move into savings, payments, and micro-insurance. We couldn’t scale like that with our old system.”

To broaden the range of services it offers, ASA International needed a regulated banking license, for which a modern core banking platform is a prerequisite. The company has also deployed Temenos Financial Crime Mitigation to reassure regulators and clients alike of its maturing responsibility.

Country by country adaptability

The key to selecting Temenos was its Financial Inclusion platform.

Temenos Financial inclusion is a great core dedicated for microfinances, with simpler screens and tailored features and functions. It was just what we needed.”

Rob Keijsers, Chief Digital and Information Officer, ASA International

Along with the modularity of the platform, it allows ASA International to easily switch-on new capabilities, on a country-by-country basis. Rob adds that this flexibility can also be applied to deployment. “We needed to take different hosting approaches for each market, in part because data sovereignty regulations vary. The underlying architecture of the platform meant we could choose cloud (Microsoft Azure) for some countries, and on-premises for others. That was a big driver for us.”

People-led implementation

Those not close to the implementation project may be forgiven for thinking it was a simple switchover; and that was the point, says Rob. “On the Friday we closed shop with our old system, and on the Monday morning we were live with Temenos, and it all worked perfectly.”

In truth, that switch-on was preceded by 12 months of hard work. Experience had taught Rob the challenge that comes with large-scale implementations, and the importance of preparation. “It’s like open-heart surgery whilst running a marathon! You’re doing all this work in the background, and having to keep your legacy system running.”

Rob points to the expertise and dedication of the Temenos team as key.

Everyone we came into contact with, from product development to technical support and account management, was phenomenal. It was a real point of differentiation for us.”

Rob Keijsers, Chief Digital and Information Officer, ASA International

Rob recalls how, having dropped its implementation partner midway through the project, Temenos helped them source Systems, who proved to be more suitable. “It’s that sort of dedication and willingness to go above and beyond that defines our relationship with Temenos.”

He says that a big lesson from the implementation project is that IT transformations are more about managing business change than deploying new systems. “I’d say 70% of implementation should focus on user adoption. The technology requires a completely different mindset, a different way of working and redesigning new processes. That’s not always easy to do if your company has been used to working in a certain way for the last 15 years.” His advice for others is to invest in training. “Train, train, and train…and not only your IT operations people, but also all your business users. Make sure that everyone is trained up to the max.”

Bigger, better, faster

The rebooted implementation exercise, which included migrating 700,000 clients in Pakistan alone, is already reaping rewards.

We have 1,000 concurrent users on the system every day, and make more than 3,000 disbursements per day. That’s a significant increase from our old system. When our loan officers come back from the field and they all start working on the system at the same time, without any hiccup, that’s an incredible step forward in reliability for us.”

Rob Keijsers, Chief Digital and Information Officer, ASA International

Rob says another long-term benefit will be the ability to standardise products and processes across the business. “That means less waste, and more focus on driving efficiencies and raising standards, both in our operations and the customer experience.” As an example, he points to the alignment of Temenos core and the company’s in-house front-end app. “Immediately that enables straight through processing (STP) and so takes out a multitude of manual, cumbersome processes. In turn, it frees up commercial resources to focus on new business opportunities.”

Agility will be another benefit. “Now we don’t have to hard-code anything into the product suite, we can make simple improvements to our products fast. That’s a big change.”

Market making

Deployment now moves to Ghana, Tanzania and Kenya (all three will be running on the Azure Cloud), expecting the first country to be live in summer 2024 and the 2 others in 2025 and then to fully rollout the platform to all remaining 9 markets.

Temenos is really investing into this market. Having such a tailored platform for inclusive finance, dedicated to microfinances, is something that Temenos does in a fantastic way that no other company matches. It illustrates that they are not simply a traditional vendor, but a partner that is helping to grow our business and the entire sector.”

Rob Keijsers, Chief Digital and Information Officer, ASA International

Contact us

Related Success Stories

CreditAccess Grameen

Scaling to serve the needs of low-income households

Bengaluru, India

CreditAccess Grameen - Success Story

Post Meta

At a Glance

  • Supported growth of 22% in the last 4 years.
  • Customer retention of 88%, among the highest in the industry
  • Processes 90,000 loan applications and 3-4m transactions every day
  • New customer onboarding cut from 20 days to less than a week
  • 11,000 new customer applications are accepted every day
  • Core banking upgrade stabilized in less than one month vs six months previously
  • New feature releases are enabled twice monthly

CreditAccess Grameen is India’s largest microfinance institution. It has 4.9m customers and manages assets of over $3.2bn. It employs 19,400 people across nearly 2,000 branches nationwide. Its mission is to be the preferred financial partner for low-income, rural households who lack access to traditional credit, with women making up more than 99.99% of its customer base. It offers a range of microfinance loan products, including business capital, home improvements, family welfare, and emergencies.

 Adapting to local challenges

Relatively low-levels of financial and digital literacy are a big challenge for India, says Sudesh Puthran, CreditAccess Grameen’s CTO. Alongside this, there is a lack of available credit history for people and a diverse mix of 20-25 native languages to cater for. That explains why CreditAccess Grameen employs a vast network of branches nationwide. “We don’t have English-speaking people sitting in our central office managing each village. Instead, we employ local people to work in each village. That fosters a greater relationship between the customer and us.”

A lack of internet connectivity is another issue that CreditAccess Grameen has had to overcome. “We have designed systems that allow our managers to process loan applications offline when connectivity is unstable, and then flush these into our core banking platform when access is back up.”

Customer-centric innovation

Fixing these challenges is the reason why CreditAccess Grameen has become the number one microfinance institution in India and is now more than twice the size of its nearest competitor. “We have designed products suitable for our customers’ situations. We understand that their reality and needs are different from urban customers, and so they need a different approach. Unlike in the city, rural populations don’t tend to get a regular monthly salary. They might get income on a weekly or daily basis, so we align our repayment schedules accordingly.” Sudesh describes this approach as customer-centric innovation.

We don’t straight-jacket our products and expect customers to adapt to them. Instead, we take time to understand their requirements and build the necessary customizations in our core banking platform. So we have gone from having a few products to having a plethora suiting everyone’s individual needs.”

Sudesh Puthran, Chief Technology Officer, CreditAccess Grameen

Low-cost growth

The approach works. CreditAccess Grameen’s annual survey of its customers has seen a steady uptick in satisfaction levels, with over 98% of customers being satisfied with our service delivery. This has driven customer retention rates of 88%. That is coupled with relatively low running costs, achieved by running an agile, lightweight, and automated operation. “We are able to manage annual growth of around 22% in the last four years without exponentially increasing headcount, including expansion into the northern states.” These efficiencies are then passed onto the customer in the form of the lowest interest rates in the market.

Pioneering technology

Since 2015 CreditAccess Grameen has used Temenos core banking to drive efficiencies. Prior to that, it relied on the integration of multiple open-source legacy solutions, which proved challenging in terms of sustainability, support, and data integrity. It was the first microfinance company in India to understand the benefits of deploying a core banking platform and was attracted to Temenos because of its specific capabilities for microfinance. “By leapfrogging onto Temenos’ core banking platform, we put all our issues to rest immediately.”

Customizability and scalability

Customizability has been a major gain. “We can offer our customers all sorts of tailored solutions. For example, flexible repayments (that align with a customer’s income cycle), loan moratoriums necessitated during the COVID-19 pandemic, the ability to perform regulatory obligations like interest subvention by the government during COVID-19 and specific state public holidays have all been easy to configure.” With ready-made lending products also accessible via the Temenos platform, such as automotive or gold-backed loans, CreditAccess Grameen has been able to significantly fasten its time-to-market for new products.

Scalability was the other reason behind CreditAccess Grameen’s decision to choose Temenos.

We process up to 90,000 loan applications every day, some as low as $12 equivalent, and 3-4 million daily transactions, so we need to have a very stable and a robust, high-performing core banking platform to deal with that sort of volume. Today, we are able to keep the business up all the time with close to zero downtimes.”

Sudesh Puthran, Chief Technology Officer, CreditAccess Grameen

One outcome has been the time to onboard new customers, which has been cut from 10-15 days to less than a week since the process was digitised and automated. With around 11,000 new customer applications being accepted every day, the efficiency savings are amplified.

Expert execution

Recently, CreditAccess Grameen has doubled down on its partnership with Temenos. It has extended its Temenos environment to Madura Micro Finance, a business it acquired; and it has upgraded to the latest version of Temenos core banking, working with Nagarro (a Temenos partner) on the implementation. “Nagarro and Temenos were great experiences overall. We had extremely strong support from Temenos to ensure the implementation went smoothly. They understood that engagement with our end business users is really important and that ongoing testing is critical to success. They were key features of both projects.”

As a result, the upgrade was considered stable after just a month from switch-on. Previously, this would take at least six months, says Sudesh. “There was hardly any downtime and we didn’t see a dip in business volume beyond 2-3 weeks, which can normally be for much more period with upgrades.”

This efficiency is carried through to new feature releases and software updates, which are enabled twice monthly. “Having a core banking platform encourages us to make these changes frequently, and keeps our business aligned with our customers’ needs.”

Deeper ties

Looking to the near future, the API architecture of the Temenos core banking platform will support CreditAccess Grameen as it moves into open banking, explains Sudesh. “The fact that we have the Temenos core banking platform will give us an edge to comply with the open API framework.” Other areas of exploration include data lifecycle management, data analytics, data lake, and Temenos Banking Cloud.

Temenos continues to be at the heart of our business.It is much more than a technology. We have a great rapport with Temenos. They are sensitive to our needs and our timeframes. They add value with every capability they provide.”

Sudesh Puthran, Chief Technology Officer, CreditAccess Grameen

We partnered successfully with Nagarro

Nagarro is a global digital engineering leader with a full-service offering, helping Temenos clients become innovative, digital-first companies and enabling them to run intelligent and agile operations powered by data and automation.

Contact us

Related Success Stories

  • LOLC Cambodia – Success Story

    LOLC Cambodia is one of the country’s largest and most mission-driven microfinance deposit-taking institutions (MDIs).

  • ASA International – Success Story

    ASA International is one of the world’s largest international microfinance institutions. It provides small, socially responsible loans to low-income entrepreneurs, most of whom are women,…

    ASA International - Success Story
  • VisionFund International – Success Story

    VisionFund International is a subsidiary of World Vision International. Established in 2003, its mission is to support children from economically disadvantaged communities by empowering families…

    VisionFund International - Temenos Success Story

Sinapi Aba

Increasing financial inclusion in Ghana with innovative services tailored to underserved client groups

Kumasi, Ghana

Sinapi Aba - Success Story

Post Meta

At a Glance

• Supports development and launch of “game-changing” services that empower disadvantaged people

• 30-35% growth year-on-year

• 1 million daily transactions and 600K accounts managed seamlessly through Temenos Core Banking for Financial Inclusion

• 63K signups for mobile banking, including 54.3% women and 33.3% from younger demographics

Since 1994, Sinapi Aba has helped financially disadvantaged Ghanaians to build a more prosperous future for themselves. Originally a non-governmental organization providing financial education, Sinapi Aba gained a license to offer savings accounts and deposits in 2013. Today, while Sinapi Aba Trust runs sanitation, apprenticeship, and mentoring programs, Sinapi Aba Savings and Loans focuses on increasing financial inclusion across Ghana.

Aaron Rex Opoku-Ahene, Chief Operating Officer at Sinapi Aba Savings and Loans, explains: “We aim to reach customer groups neglected by larger financial institutions. These include micro, small and medium-sized enterprises [MSMEs], which are often run by women, as well as farmers in isolated rural locations. Our goal is to help them to expand their businesses, build homes, pay their bills, and support their families and local community.”

Hitting roadblocks on the growth journey

Previously, Sinapi Aba managed its lending and savings operations using spreadsheets, stored locally on devices at branches. However, if a device malfunctioned or an authorized user was unavailable to access the right file, business was disrupted and customers requesting a statement went away disappointed. This technology model also made it difficult to scale operations.

King Asante-Frempong, Head of IT/MIS at Sinapi Aba Savings and Loans adds: “For every new customer, we had to create and maintain a new spreadsheet to record transactions and loan repayments. As we expanded, this was becoming unsustainably complex. And relying on legacy systems also restricted our ability to innovate, which was essential for us to bring financial services to more people, especially those that could not easily get to our branches.”

The operating model had drawbacks for internal efficiency and transparency, too. “Preparing close-of-business (COB) and end-of-month reports on our overall lending performance was tough. A member of our team would have to pull together all the spreadsheets from our branches and then calculate consolidated figures, which was very time-consuming, tedious, and error-prone work,” adds King Asante-Frempong.

Adopting a more agile and robust business model

To increase its outreach to underserved communities, Sinapi Aba decided to modernize its technology capabilities. The objective was to replace spreadsheets with a scalable core banking platform supported by a central customer database. After assessing potential solutions, Sinapi Aba selected Temenos Financial Inclusion.

“The modern client-server architecture of the Temenos solution would allow us to transform our operations and adopt more agile ways of working. And the robust processing capabilities were ideal to support high volumes of transactions. Plus, Temenos offered a choice of certified partners with years of experience working with African financial institutions to roll out the platform and train our users.”

King Asante-Frempong, Head of IT/MIS, Sinapi Aba Savings and Loans

Accessing leading-edge core banking capabilities

Since the initial deployment, Sinapi Aba has worked with STRAJ Solutions to complete multiple upgrades of the Temenos platform, enabling access to the latest functionality, integration, and support. Among the most important enhancements that the microfinance institution has gained with recent releases are non-stop 24/7 transaction processing capabilities and a more intuitive browser-based user interface.

The latest Fixed Assets module in Temenos core banking is really useful, enabling us to automate accounting tasks and remove a lot of headaches for the finance team. Recent upgrades have also streamlined our backup strategy, which helps ensure customer data always remains secure and available.”

King Asante-Frempong, Head of IT/MIS, Sinapi Aba Savings and Loans

Temenos Financial Inclusion also simplifies data analytics and report generation for Sinapi Aba. Rather than spending time scraping data from complex spreadsheets, business users can quickly create reports for senior stakeholders that provide insights into the COB or end-of-month position, the overall performance of the lending portfolio, and other key metrics, such as operational costs.

At any time, Sinapi Aba can call on STRAJ Solutions for additional support. “The training from STRAJ Solutions was excellent, so we have a strong knowledge of Temenos core banking and the Financial Inclusion configuration. Whenever we face challenges, they provide great service and quickly bring in help from Temenos when required,” adds King Asante-Frempong.

Bringing financial services to clients in isolated regions

Sinapi Aba is using the open API capabilities of Temenos core banking to innovate and launch new customer services. For example, the microfinance institution has integrated its core banking platform with the Ghana Interbank Payments and Settlements System managed by the country’s central bank—enabling customers to make instant transfers from their Sinapi Aba account to other banks or digital wallets.

In another major initiative, Sinapi Aba used Temenos to develop a mobile banking platform specifically for underserved customer groups. Available as an iOS or Android app or a USSD service, the mobile offering gives users a secure, accessible, and convenient way to make loan repayments, check savings accounts, pay bills, transfer funds, and more. It also offers access to a series of ‘How-to’ educational videos in multiple languages that help to increase financial literacy and build confidence in managing money.

Although only launched recently, Sinapi Aba has recorded a total of 63,000 customer signups for the mobile banking offering, with 65,000 transactions being made through the app and USSD service every month. In total, 54.3 percent of users are women, and 33.3 percent are from younger demographic groups. Sinapi Aba believes the mobile offering will be a game-changer for financial inclusion.

Our innovative mobile service helps us reach people in isolated rural areas that cannot visit a branch; instead, we are taking banking to their doorway. We offer access to valuable tools that empower MSMEs to bank their daily takings, or for women to save and build a safety net for their families in case of adversity.”

Aaron Rex Opoku-Ahene, Chief Operating Officer, Sinapi Aba Savings and Loans

Reaching more and more disadvantaged Ghanaians

Today, Sinapi Aba uses Temenos Financial Inclusion to support operations at 44 branches, manage more than 600,000 accounts, and process more than one million daily transactions. “We are achieving an average yearly growth of 30 to 35 percent and consistently hitting our targets,” adds Aaron Rex Opoku-Ahene. “One key factor behind this growth is having a reliable, scalable core system that allows us to manage more and more transactions seamlessly.”

King Asante-Frempong concludes: “We have worked with Temenos and STRAJ Solutions for more than 20 years now, and they remain valuable partners to us and an important part of our success. Temenos Financial Inclusion enables us to develop innovative services that increase financial inclusion and help hundreds of thousands of disadvantaged Ghanaians to achieve a brighter and happier future for themselves.”

We partnered successfully with:

STRAJ have walked the digital transformation journey with Temenos clients since 2002, enabling them derive optimum value from their investment in the technology of the day.


Contact us

Related Success Stories

  • LOLC Cambodia – Success Story

    LOLC Cambodia is one of the country’s largest and most mission-driven microfinance deposit-taking institutions (MDIs).

  • VisionFund International – Success Story

    VisionFund International is a subsidiary of World Vision International. Established in 2003, its mission is to support children from economically disadvantaged communities by empowering families…

    VisionFund International - Temenos Success Story
  • ASA International – Success Story

    ASA International is one of the world’s largest international microfinance institutions. It provides small, socially responsible loans to low-income entrepreneurs, most of whom are women,…

    ASA International - Success Story

Hope International

Alleviating poverty in underserved communities with innovative microfinance services

Pennsylvania, United States

Hope International - Success Story

Post Meta

At a Glance

• Scalable, robust platform upon which to build and integrate innovative solutions

• Exceptional foundation that allows HOPE to continuously adapt and expand digital services

Side view of woman sitting on a chair. Her laptop is resting on the small table in front of her. She is participating in a video call.

HOPE International is a leading Christian non-profit organization that invests in the dreams of families among the world’s underserved communities. Motivated by the teachings of Jesus Christ, Hope International provides microfinance services, savings programs, and training that help individuals and small- and medium-sized business owners to escape poverty.

Launched in 1997, HOPE International has served more than 2.5 million people worldwide since inception. Headquartered in Pennsylvania, USA, the organization’s microfinance operations and partnerships cover Eastern Europe, South America, Africa, and South Asia, and has disbursed over $100 million USD in loans over its 25-year history.

Our microfinance institutions help underserved people to build better lives for themselves and their families. We do this through providing loans and savings opportunities to entrepreneurs. We also work alongside of the church to create savings groups in their communities.”

Emmanuel Wuver, Managing Director, HOPE International

Clearing the way to growth

In Africa, HOPE International operates microfinance institutions in three locations: Rwanda, Burundi, and the Republic of the Congo. Recently, the organization has focused more on digital service delivery to reach communities in more remote regions and to create greater efficiencies in operations.

Emmanuel Wuver continues: “We now use our in-house built digital field applications to take customer registration, loan applications, and repayments to people rather than relying on them to come our branches. We are also pursuing an ambitious innovation program, featuring new services and an enhanced client experience.”

Previously, Hope International relied on a suite of legacy applications to develop products and process transactions across multiple microfinance institutions. The organization found tasks such as launching new services, preparing reports and tracking loan repayments complex and time-consuming, and supporting differing platforms was inefficient.

“We had gone as far as we could with our old systems,” adds Emmanuel Wuver. “We decided to look for an alternative that would support our innovation and outreach plans. For example, we were keen to integrate our digital field application and mobile banking channels with third-party solutions—including leading-edge fintech tools—to form a more user-friendly, accessible ecosystem of microfinance services.”

Implementing a platform tailor-made for microfinance

To improve operations at its three African microfinance institutions, HOPE International decided to deploy Temenos Financial Inclusion. Purpose-built to help non-bank financial institutions increase their outreach, the scalable, packaged Temenos solution provides integrated core banking, analytics, and digital channels functionality, and pre-configured workflows to reduce time to value.

Emmanuel Wuver explains: “The Temenos solution offers efficiencies to our work, along with configurable product development frameworks to accelerate innovation. We were also impressed with the open APIs, which make it easier to connect with our commercial partners. The extensive experience of Temenos in the microfinance space was another attraction.”

HOPE International implemented the solution with support from Temenos. The organization started in Rwanda, going live with Temenos Financial Inclusion in just 14 months. Next, HOPE International began the process in Burundi, using a remote deployment process due to pandemic restrictions. After a successful deployment in Burundi, the HOPE team used a hybrid deployment process to implement the solution at their operations in the Republic of the Congo.

We greatly appreciate the support of the Temenos team throughout the challenges of each implementation. Applying the lessons learned in Rwanda allowed us to go live in Burundi and the Republic of the Congo much faster, despite the impact of the pandemic.”

Emmanuel Wuver, Managing Director, HOPE International

Bringing financial services to people in need

Today, Temenos Financial Inclusion plays a key role in supporting HOPE International’s African microfinance operations. The organization uses the platform for supporting branch services, processing transactions across multiple application channels, managing loan disbursements and payments, and more.

“Our business teams appreciated the flexibility of the Temenos platform, including adding new menus and building product workflows to fit their needs,” adds Emmanuel Wuver. “We have especially appreciated the ability to build internally on the Temenos platform, enabling us to better equip our staff and significantly enhance our operations.”

The organization has launched internal applications for customer registration, loan applications, and loan repayments that have been integrated with the Temenos platform. Additionally, HOPE has been able to connect the Temenos platform with multiple third-party software applications, including mobile banking and government services.

The engagement with Temenos has also helped HOPE International achieve it’s goal to increase its outreach, as Emmanuel Wuver confirms: “Connecting the Temenos platform with our digital field application allows us to bring new services to people in remote communities. The solution really helps us in our mission to alleviate poverty and support people in need.”

Embracing leading-edge fintech solutions

Moving forward, HOPE International intends to harness the API capabilities of Temenos Financial Inclusion to continue to improve its microfinance services. For example, the organization is planning to integrate with innovative fintech tools for credit scoring and identity verification.

Many of our strategic plans build upon the Temenos platform. We really value the responsive service we receive from Temenos, especially from the Temenos Product Director for Financial Inclusion. We’re grateful for the partnership and support the Temenos team has for our mission to help underserved communities.”

Emmanuel Wuver, Managing Director, HOPE International

Contact us

Related Success Stories

  • LOLC Cambodia – Success Story

    LOLC Cambodia is one of the country’s largest and most mission-driven microfinance deposit-taking institutions (MDIs).

  • VisionFund International – Success Story

    VisionFund International is a subsidiary of World Vision International. Established in 2003, its mission is to support children from economically disadvantaged communities by empowering families…

    VisionFund International - Temenos Success Story
  • ASA International – Success Story

    ASA International is one of the world’s largest international microfinance institutions. It provides small, socially responsible loans to low-income entrepreneurs, most of whom are women,…

    ASA International - Success Story

St. Raphael’s Garda Credit Union – Success Story

Fostering long-term loyalty with seamless, always-on digital services for the Irish police force and their families

Dublin, Ireland

St. Raphael's Garda Credit Union - Success Story

Post Meta

At a Glance

• 80% year-on-year increase in new registrations for digital services

• 35% of loans originate on the digital channel within just 10 months after go-live

• 40% drop in call-center volumes, freeing teams up to support members more comprehensively

• 85% reduction in manual back-end processing, reducing the risk of human error

• 83% Net Promoter Score, reflecting member satisfaction and loyalty.

Established in 1964, St Raphael’s Garda Credit Union was formed to serve the needs of An Garda Síochána, Ireland’s national police force. From a membership of 119 people in its first year, the organization has grown to become the country’s largest credit union, now made up of more than 39,000 Gardaí and their families.  A not-for-profit co-operation, the organization has a member-centric approach to its business.

Claire Byrne, Chief Executive Officer at St Raphael’s Garda Credit Union, says: “We serve almost every part of the police force, with members living all across Ireland. What sets us apart from other financial institutions are the deep relationships we cultivate with our members which have been built on more than fifty years of mutual trust and respect. Our primary objective is to look after the financial well-being of all our members, and we work hard to truly understand each member’s needs, and to offer them best-in-class lending and savings products and services to help them achieve their financial goals.”

Meeting new expectations

In recent years, consumer expectations around financial services have shifted dramatically. Today, customers increasingly expect the ability to engage with their provider on any channel—branch, contact center, or digital device—and to switch between these channels seamlessly throughout their journey.

“As a not-for-profit co-operative, we can provide lending and savings products at extremely competitive rates, since we’re not dependent on external money markets” explains Claire Byrne. “While great prices, service levels and products are crucial, easy access and speed of decision has become increasingly important and therefore constant investment in how we deliver our services has also become equally important. In Ireland and around the world, the financial services sector is evolving rapidly. As digital banking becomes the norm and new entrants such as fintechs enter the marketplace, it’s vital for St Raphael’s to offer high-quality online and mobile experiences to compete effectively and ensure we remain central in the provision of financial services for our members.”

Targeting digital transformation

To realize its goals, St Raphael’s set out on a far-reaching digital transformation. The aim was to provide members with streamlined digital services: empowering online and mobile users to complete important journeys such as loan origination end to end. St Raphaels will always offer members a choice in the channels they choose to use, whether that is to visit a branch, call a customer service agent, or to utilize our digital channels.

We never take our members’ loyalty for granted. To help us to attract new members and protect hard-won relationships, we decided to reimagine our digital channel from the ground up.”

Claire Byrne, Chief Executive Officer, St Raphael’s Garda Credit Union

Selecting a proven partner

For many years, St Raphael’s has been a leading innovator in Ireland’s financial services industry. When Ireland’s regulatory framework for credit unions was updated, the organization was the first to offer mortgage products to its members. The company was also an early adopter of digital services, working with Temenos to support its first online banking experience using an earlier version of Temenos core banking more than a decade ago. Based on its positive experiences with Temenos Financial Inclusion solution, the credit union decided to build its new digital experiences on the latest generation of the Temenos core banking solution along with Temenos digital banking platform.

“To realize our vision for the omni-channel customer experience, we targeted even tighter integration between our front, middle and back office – and that’s exactly what Temenos allows us to do,” comments Claire Byrne. “As a small business, we greatly appreciate the wealth of technical expertise and customer experience best practices that our partnership with Temenos brings to St Raphael’s. Crucially, with Temenos front-to-back platform, we can deliver consistent journeys across every channel and digital device.”

Realizing the vision

Working with its Temenos business partner Banktech, St Raphael’s mapped out the target workflows and configured Temenos core and digital banking platform to enable the new omni-channel experiences. The solution includes an entirely digital process for loan origination—the first of its kind for any credit union in Ireland.

“Our transformation was complex, and the process was further complicated by the disruption of the COVID-19 pandemic, which struck right in the middle of the project,” recalls Claire Byrne. “Despite the challenges we faced, the excellent collaboration between our team, Banktech and Temenos helped us to keep our work on track. Although social distancing and lockdown measures forced us to switch from a co-located project team to colleagues working remotely from the UK, India, and the USA, we were determined to succeed—and our switchover to the new solution went very smoothly.”

Ensuring 24/7 services

Today, St Raphael’s uses Temenos Financial Inclusion to support its core banking workflows from end-to-end, while Temenos digital banking platform allows the organization to deliver outstanding digital experiences to its members, online and on mobile.

“The transition to the latest version of Temenos core banking was practically seamless for St Raphael’s employees,” comments Claire Byrne. “The Temenos solution is extremely intuitive, which allowed our people to get started with minimal training. Most importantly, the solution is also extremely resilient and reliable.  Our members are front-line staff, working 24 hours a day, seven days a week. We need a service that is resilient and reliable, and Temenos core banking enables us to keep our services running smoothly 24 hours a day.” Thanks to intelligent automation powered by our Temenos solutions, members can now apply for lending products from their smartphone and receive an approval within minutes—any time, day or night. After just 10 months, a massive 35% of all our loans now originate on the digital channel, which is a testament to the value our members see in the service.”

Accelerating adoption, generating operational efficiencies, and reducing risk

St Raphael’s members have been quick to embrace the new online and mobile experiences. The organization has measured an 80% year-on-year increase in new registrations for its digital services, and an increasing number now seek out these channels for day-to-day transactions.

Members now have the freedom to carry out their business at the times that are most convenient for them. As a result, we’ve seen a 40% drop in call volumes to our contact centre. Our teams now have more time to help people with more complex needs.  And members have responded really well to these improvements, rating St Raphael’s with an incredible Net Promoter Score of 83% in a recent survey.”

Claire Byrne, Chief Executive Officer, St Raphael’s Garda Credit Union

Automation at St Raphael’s isn’t limited to customer-facing services. Behind the scenes, Temenos core banking allows back-office teams to work more efficiently than ever. Claire Byrne confirms: “One of the impacts of the new solution that we didn’t fully anticipate at the beginning of the project was just how much time it would save in the back office—, particularly around regulatory controls. Automation has allowed us to reduce manual processing by around 85%, which cuts the risk of human error and liberates our teams to focus on value-added work.”

Looking to the future

Looking ahead, St Raphael’s plans to build on its success with Temenos and drive continuous enhancements to the customer experience. The next step is the move to the cloud, in collaboration with Temenos.

The impact of our transformation has been phenomenal: we can now deliver even higher-quality services to our customers without driving up cost and complexity for the business. In our sector, continuous innovation is crucial to compete effectively. We wouldn’t hesitate to recommend Temenos, and we look forward to working with them to find new ways to improve our services.”

Claire Byrne, Chief Executive Officer, St Raphael’s Garda Credit Union

Temenos Ambassador Awards 2022

Delighted to recognize St. Raphael’s Garda Credit Union as one of the winners of the Innovation Hero Awards for deploying an innovative and impactful project, using a Temenos solution.

We partnered successfully with Banktech Software Services

Banktech offers end-to-end implementation services covering all Temenos Products Suites. Banktech offers agile implementation services thus fast tracking digital transformation for Banks

Contact us

Related Success Stories

  • Hamilton Reserve Bank – Success Story

    Hamilton Reserve Bank serves a large and rapidly growing global clientele from its 12-acre bank headquarters in Nevis, the birthplace of America’s founding father Alexander Hamilton.

  • IRACE Digital – Success Story

    IRACE Digital leverages Temenos SaaS for global digital banking, offering secure, paperless onboarding and scalable multi-market operations.

  • Bank Albilad – Success Story

    Bank Albilad was the first bank in the Kingdom of Saudi Arabia to offer Shari’ah-compliant products. The bank provides services to retail, corporate, and SME…

    Bank Albilad - Success Story

Enda Tamweel

Improving the level of automation

Tunis, Tunisia

Post Meta

Enda Tamweel, a leading microfinance institution in Tunisia, with 96 branches, 5 mobile branches, and over 1,800 staff has grown considerably over the last 30 years, supporting close to 900,000 customers over this timeframe. Enda has gone live with cloud-native, cloud-agnostic Temenos core banking, making Enda the ninth Temenos customer in Tunisia, demonstrating Temenos’ expertise and knowledge of the Tunisian market to fulfill its objective of contributing to the financial inclusion of millions of Tunisian entrepreneurs and offering diversified services and lines of credit.

We are delighted with our new digital core banking system. On the day the platform went live we were able to connect more than 1,400 users and make 1,900 transactions, which really reinforces how effective the transformation has been from day one. For us, speed of response to customers is critical. It can mean the difference between someone being accepted for a loan and being able to start a small business, and limiting the numbers of people we can help. Thanks to Temenos core banking, we have been able to make a greater impact in helping people to grow and sustain their businesses and as a result, improve their living conditions and those of their families.”

Mohamed Zmander, Chief Executive Officer, Enda Tamweel

Enda selected Temenos core banking to provide the agility to service more customers at a lower cost, and to quickly launch new products and services. Over the years, Enda’s former open-source information system has become unable to respond to the evolving needs of the institution. With Temenos’ pre-configured micro-finance capabilities, Enda is now also able to process large volumes of transactions efficiently and provide a better customer experience.

Contact us

Related Success Stories

  • LOLC Cambodia – Success Story

    LOLC Cambodia is one of the country’s largest and most mission-driven microfinance deposit-taking institutions (MDIs).

  • ASA International – Success Story

    ASA International is one of the world’s largest international microfinance institutions. It provides small, socially responsible loans to low-income entrepreneurs, most of whom are women,…

    ASA International - Success Story
  • CreditAccess Grameen – Success Story

    CreditAccess Grameen is India’s largest microfinance institution. It has 4.9m customers and manages assets of over $3.2bn. It employs 19,400 people across nearly 2,000 branches…

    CreditAccess Grameen - Success Story

Nuestra Caja

Reaching Mexican citizens traditionally overlooked by major banks

Oaxaca, Mexico

Nuestra Caja (NUCA) - Success Story

Post Meta

Nuestra Caja launched more than two decades ago with a crystal-clear goal: to deliver financial services to low-income citizens who struggle to access the resources needed to achieve economic security. In short, the cooperative (caja) aims to drive financial inclusion within Mexico and to improve the lives of its customers and their families.

In Mexico, cajas populares play a similar role to member-owned financial cooperative (caja) societies in the United States and Europe. Despite successful initiatives run by the Bank of Mexico, research from the International Monetary Fund (IMF) reveals there are still millions of people in Mexico without regular access to basic financial services. This is especially true for female citizens and those living in the south-eastern states, which is precisely where Nuestra Caja operates.

Moises Cruz Matias, President of the Board of Directors at Nuestra Caja, explains: “To succeed, we need to reach those sections of society that have been overlooked and underserved by the major banks. That means offering a service proposition that appeals to the likes of small traders, seasonal workers in rural areas, and female citizens, who favor flexible credit agreements and repayment terms.”

Making a fresh start

For Nuestra Caja, the priority is to offer high-quality, user-friendly credit, lending, savings and investment products that align with the aspirations of their target customers. The inevitable challenge is how to marry this focus on innovation with cost-efficiency to ensure that the cooperative (caja) stays competitive commercially.

As it expanded its customer base, Nuestra Caja encountered a familiar problem for financial institutions. The core systems that support its corporate and branch operations were becoming increasingly difficult to scale, manage and maintain. Nuestra Caja decided the time was right to make a clean break and implement a more advanced core platform.

“We realized that continuing with our aging systems would make it harder and harder to achieve our goals,” says Moises Cruz Matias. “We struggled to add new functionality to help us extend our offering, increase efficiency, and create a more compelling in-branch experience. To continue our growth, we looked to modernize using the latest technology.”

Pinpointing the right partner

Nuestra Caja engaged a specialist IT consultancy to provide guidance on the best core solutions available and a series of assessment benchmarks. The cooperative (caja)’s key criteria for the new solution included first-rate reliability and scalability, a clear upgrade plan to ensure access to the latest core functionality, and the availability of expert technical support to assist its development teams. Having analyzed the market, Nuestra Caja identified a standout candidate to replace its distributed legacy systems: Temenos Core. The cooperative (caja) implemented the Temenos platform across its network of 50 branches and at its corporate offices—providing capabilities for streamlined management of lending activities, greater control of credit risk, flexible product design, and standardized branch teller operations. And for the first time, the cooperative (caja) can now monitor credit risk and view account balances in real time.

Reaping the benefits

Since the initial go-live, Nuestra Caja has seen exceptional results. Take product development, for example. Previously, the cooperative (caja)’s outdated legacy applications hampered development efforts and time to market for new services. The Temenos platform simplified and accelerated this process, providing a set of flexible components that Nuestra Caja uses to create unique lending and savings products tailored to appeal to target customer groups.

Today, we can bring a new product to market within one week, which represents a huge improvement. With Temenos Transact, we can continually evolve and refine our services, ensuring that we offer the most compelling proposition to potential customers. In fact, since we implemented the Temenos platform, we have doubled our overall customer base and seen our lending business expand by 30 percent, establishing us as a key service provider in the region.”

Moises Cruz Matias, President of the Board of Directors, Nuestra Caja

Beyond these high-level business benefits, Nuestra Caja can also rest assured that it has a robust core platform in place that will keep its operations running round-the-clock without the risk of disruption. What’s more, the Temenos solution provides a clear upgrade path, ensuring the cooperative (caja) can continue to enhance the capabilities of the core platform. And by standardizing operations on a single, proven platform, Nuestra Caja eliminated the cost and effort of maintaining multiple legacy systems.

Fostering collaboration and knowledge transfer

Working with Temenos also yields another valuable outcome for Nuestra Caja: an annual invite to the Temenos Community Forum. The cooperative (caja) takes advantage of this opportunity to meet with leading players from the financial services world, explore the latest new software functionality and best practices, and discover how other clients are making the most of their investments in Temenos technologies.

Moises Cruz Matias continues: “As a relatively small player in the financial services industry, the chance to gain insights from the global leaders is really valuable to our ongoing growth strategy. Add to this that our internal development teams can access first-rate technical assistance and thought leadership from Temenos experts at any time to support our own innovation projects.”

As it stands today, Nuestra Caja has built a base of more than 101,000 customers, 93 percent of which are women.

Our partnership with Temenos has been integral to our success in bringing financial services to more and more low-income Mexicans. We would recommend Temenos to any other cooperative (caja) or bank considering how to transform their core systems today. You can feel confident in the expertise of their consultants and the quality of their solutions—you will not regret your decision.”

Moises Cruz Matias, President of the Board of Directors, Nuestra Caja

Contact us

Related Success Stories

  • Bank Syariah Indonesia (BSI)

    Bank Syariah Indonesia (BSI) is the largest Islamic bank in Indonesia. Established in 2021 through the merger of three state-owned Islamic banks, BSI now serves more than 23 million customers and manages approximately IDR 456 trillion (US $27B) in assets.

    Bank Syariah Indonesia (BSI)
  • Bank ABC – Success Story

    Founded in 1980, Bank ABC has grown into a leading international banking powerhouse serving customers in 25 markets through a network spanning 15 countries across the Middle East, North Africa, Europe, the Americas, and the Far East.

  • Banco da Amazônia – Caso de sucesso

    Descubra como o Banco da Amazônia modernizou seu core bancário com a Temenos para ampliar serviços digitais, aumentar a eficiência e impulsionar o crescimento.