For most banks, the hardest part of digital delivery has never been the core. It is the customer experience layer: the screens, journeys and integration work that turn core systems into something a person can use. That layer absorbs the bulk of implementation effort, which is why a roadmap agreed in January can still be unbuilt in December.
Generative AI in banking is reducing that constraint. When a working, connected customer journey can be produced in hours rather than months, the build stops being the hardest part. The harder questions become what to build, in what order, and how to govern it at speed. Institutions that plan for that shift will get more from AI than those that attempt to run the old process faster.
Faster building exposes slower decisions
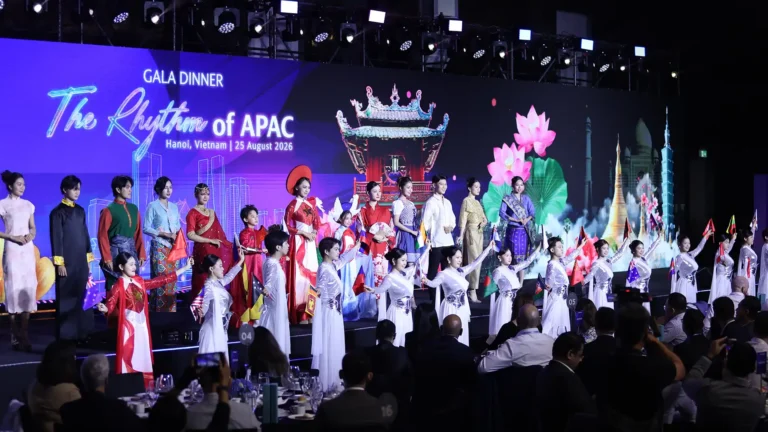
A customer journey demonstration at a recent Temenos event in Hanoi showed how quickly the development process is moving. A plain-language description of a retail banking experience became a multi-screen application in minutes, connected to core banking APIs and responsive across mobile, tablet and desktop. A single follow-up prompt added Arabic with right-to-left layout and multi-currency support. The code then went into source control and through automated testing towards QA.
The technology is only half the story. When build time shrinks, the steps that once sat unnoticed inside a six-month project move onto the critical path: approval cycles, compliance reviews, prioritization debates. A bank that can generate a new journey in a day but needs eight weeks to agree on it has moved its bottleneck, not removed it.
Governance works best inside the build, not after it
Speed without control is not a conversation any risk committee will entertain. The more useful shift is governance that travels with the work rather than waiting at the end of it.
In the same demonstration, a designer changed a colour and the system flagged a WCAG accessibility issue, then offered a fix on the spot. New features respected the user entitlements the bank had already defined. The generated code sat in the bank’s own repository, where developers could review it line by line.
Small moments, but they point to a different model. Checks happen continuously, people stay in the loop where judgement matters, and traceability exists from day one rather than being reconstructed before an audit.
Complexity no longer has to grow with ambition
Every new segment, market or partner has traditionally meant another build, and with it more testing, more maintenance and more technical debt. Across Asia Pacific, where language diversity and regulatory variation are the norm, that cost compounds quickly.
When variants become adaptations of one shared experience rather than parallel builds, growth stops multiplying the maintenance burden. That frees capacity for the work that genuinely differentiates.
Where institutions are starting
Banks making early progress tend to share a few habits:
- They make prioritization a discipline, keeping a clear view of which customer journeys matter most so faster delivery lands in the right places.
- They bring risk, compliance and design into the iteration loop early, shortening decision cycles alongside build cycles.
- They insist on ownership, requiring AI-generated code to be transparent, reviewable and held in the bank’s own environment.
- They start with one high-value journey and prove the model before scaling it.
Standing still carries its own cost. Customers compare their bank with the best digital experiences in any industry, and faster-moving competitors iterate weekly. The gap between intent and delivery is becoming visible to the people who matter most.
A better problem to have
The next phase of digital banking will not be defined by who can build fastest. That advantage is becoming available to everyone. It will be defined by who can decide well, govern confidently and focus capacity on what customers actually need.
For digital leaders, the hardest question is shifting from “how do we build this?” to “what should we launch next?” That is a far better problem to have.
Explore the Temenos perspective of the Bank of Tomorrow and discover how AI, intelligent automation and digital experiences are reshaping customer engagement, service delivery and banking innovation.
Describe the journey.
Watch it build itself.
Banks across Asia Pacific are turning natural-language intent into production-ready digital journeys — in days, not months. See how, and get the data behind it.