
Temenos Announces Q3-26 Results; FY-26 Guidance Raised
- Q3-26 ARR of USD 904m, up 12% y-o-y c.c.
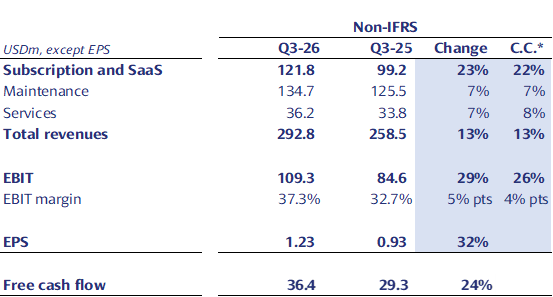
- Non-IFRS Q3-26 product revenue up 14% c.c.
- Non-IFRS Q3-26 subscription and SaaS of USD 122m, up 22% c.c.
- Non-IFRS Q3-26 maintenance up 7% c.c.
- Non-IFRS Q3-26 EBIT up 26% c.c. with 4 points of margin expansion
- Non-IFRS Q3-26 EPS up 32% reported
- Q3-26 free cash flow (FCF) of USD 36m, up 24% reported
- FY-26 EBIT and EPS guidance raised, guidance reconfirmed for ARR, subscription & SaaS and FCF
- FY-28 targets reconfirmed
Ad hoc announcement pursuant to Art. 53 LR
GRAND-LANCY, Switzerland, October 27th, 2026 – Temenos AG (SIX: TEMN), a global leader in banking technology, today announced its third quarter 2026 results.
Commenting on the results, Temenos CEO, Takis Spiliopoulos said:
“We saw good underlying business momentum in the third quarter, supported by a stable sales environment, and we signed all of the revenue that had slipped from the second quarter. Subscription and SaaS revenue growth was impacted by one large deal in Africa signing in the first days of Q4-26. We continue to expand our large deal execution capabilities to improve execution consistency and, with a strong pipeline of deals, are confident in delivering our full-year guidance.
Our recurring revenue base has continued its consistent growth trajectory, with ARR up 12% and subscription and SaaS revenue up 22% in constant currency. We also delivered strong growth in profitability, with EBIT up 26% and four points of margin expansion, and EPS up 32% driven by efficiency savings, good cost control and operating leverage, while free cash flow grew 24%.
Looking at the regions, I was particularly pleased with the performance in Europe, including the signing of a large deal with a global tier 1 bank for its European operations. We also had a good performance in the Middle East, signing multiple deals with new and existing customers and continue to build momentum in North America with four new SaaS deals, including a deal with a regional US bank signed early in the third quarter, and a large deal in Canada.
We continue to make good progress on our strategic priorities. The integration of additiv is progressing well, with a new tier 1 bank deal signed in APAC, while our Product & Technology leadership team is accelerating the delivery of our product roadmap and innovation.
We delivered sizeable efficiency savings and maintained good cost discipline in the quarter and with the continued momentum in the business, we are raising our FY-26 guidance for EBIT and EPS, while reconfirming our guidance for ARR, subscription and SaaS and free cash flow growth. We are also reconfirming our FY-28 targets.”
Annual Recurring Revenue (ARR)
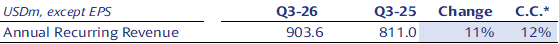
Note: *Constant currency (c.c.) adjusts prior year for movements in currencies
Income statement and free cash flow
Note: The definition of non-IFRS adjustments is provided below. *Constant currency (c.c.) adjusts prior year for movements in currencies
Business update
- Stable sales environment throughout the quarter, with all slipped revenue from Q2 closed in Q3
- Q3-26 subscription and SaaS revenue growth impacted by one large deal in Africa signing in the first days of Q4-26
- Strong underlying momentum with a good number of new logos and SaaS ACV signings across regions
- Europe performing particularly well, signing a number of deals including a large deal with a global tier 1 bank for its international operations
- Middle East also performed well, signing multiple deals with new logo and existing customers across the Gulf region
- Strong SaaS momentum in North America with four new logo deals, including a deal with a regional US bank and a large deal in Canada
- Good progress on integration of additiv, with new tier 1 bank deal signed in APAC
- Strong growth in profitability from AI-driven efficiency savings, good cost control and operating leverage, and strong double-digit free cash flow growth
- Robust start to the fourth quarter and good visibility driven by a strong pipeline
- FY-26 guidance raised with non-IFRS EBIT growth of c.12% (c.c., up from c.9%) and EPS growth of c.10% (reported, up from c.7%); guidance reconfirmed for ARR growth of c.12% (c.c.), non-IFRS subscription & SaaS revenue growth of c.9% (c.c.), and FCF growth of c.16% (reported)
- FY-28 targets reconfirmed
Revenue
Reported IFRS revenue was USD 292.5m for the quarter, and non-IFRS revenue was USD 292.8m for the quarter, both increasing by 13% vs. Q3-25.
Reported IFRS subscription and SaaS revenue for the quarter was USD 121.7m, and non-IFRS subscription and SaaS revenue for the quarter was USD 121.8m, both increasing by 23% vs. Q3-25.
EBIT
Reported IFRS EBIT was USD 84.8m for the quarter, an increase of 41% vs. Q3-25.
Reported non-IFRS EBIT was USD 109.3m for the quarter, an increase of 29% vs. Q3-25.
Earnings per share (EPS)
Reported IFRS EPS was USD 0.92 for the quarter, an increase of 42% vs. Q3-25.
Non-IFRS EPS was USD 1.23 for the quarter, an increase of 32% vs. Q3-25.
Cash flow
USD 36.4m of free cash flow was generated in the quarter, an increase of 24% vs. Q3-25.
FY-26 non-IFRS guidance
Temenos raises its FY-26 guidance. The guidance for FY-26 is non-IFRS and in constant currencies, except for EPS and FCF which are reported. The acquisition of additiv is expected to be marginally accretive to Temenos’ FY-26 ARR and non-IFRS subscription and SaaS guidance and is expected to be neutral for Temenos’ FY-26 EBIT, EPS and FCF guidance. Growth rates are versus FY-25 proforma (excluding Multifonds).
- ARR growth of c.12% c.c.
- Subscription and SaaS growth of c.9% c.c.
- EBIT growth of c.12% c.c. (up from c.9%).
- EPS growth of c.10% reported (up from c.7%).
- FCF growth of c.16% reported
FY-26 guidance includes a negative headwind on growth from the termination of one BNPL client in FY-25. There is no further headwind from this termination after FY-26. The impact is as follows:
- 3% pts on ARR
- 5% pts on subscription & SaaS
- 4% pts on EBIT and EPS
Currency assumptions for FY-26 guidance
In preparing the FY-26 guidance, the Company has assumed the following:
- EUR to USD exchange rate of 1.12;
- GBP to USD exchange rate of 1.34; and
- USD to CHF exchange rate of 0.82
The Company has also assumed the following for FY-26 guidance:
- FY-26 tax rate expected to be between 19-21%
FY-28 targets
Temenos reconfirms its FY-28 targets. These targets are organic and non-IFRS, and do not include any contribution from additiv.
- ARR of at least USD 1.23bn
- EBIT of c.USD 480m
- FCF of c.USD 410m
The guidance provided above and other statements about Temenos’ expectations, plans and prospects in this press release constitute forward-looking financial information and represent the Company’s current view and estimates as of October 27th,2026. We anticipate that subsequent events and developments may cause the Company’s guidance and estimates to change. Future events are inherently difficult to predict. Accordingly, actual results may differ materially from those indicated by these forward-looking statements as a result of a variety of factors. More information about factors that potentially could affect the Company’s financial results is included in its annual report available on the Company’s website.
Conference call and webcast
At 18.30 CET / 17.30 BST / 12.30 EST today, October 27th, 2026, Takis Spiliopoulos, CEO and Daniel Schmucki, CFO, will host a webcast to present the results and offer an update on the business outlook. The webcast can be accessed through the following link:
Please use the webcast in the first instance to avoid delays in joining the call. For those who cannot access the webcast, the following dial-in details can be used as an alternative. Please dial in 15 minutes before the call commences.
Switzerland / Europe: + 41 (0) 58 310 50 00
United Kingdom: + 44 (0) 203 059 58 63
United States: + 1 (1) 631 570 56 13
Non-IFRS financial information
Readers are cautioned that the supplemental non-IFRS information presented in this press release is subject to inherent limitations. It is not based on any comprehensive set of accounting rules or principles and should not be considered as a substitute for IFRS measurements. Also, the Company’s supplemental non-IFRS financial information may not be comparable to similarly titled non-IFRS measures used by other companies. The Company’s non-IFRS figures exclude share-based payments and related social charges costs, any deferred revenue write-down resulting from acquisitions, discontinued activities that do not qualify as such under IFRS, gain/loss from business disposals, acquisition/investment/carve out related charges such as financing costs, advisory fees and integration costs and fair value changes on investments, charges as a result of the amortization of acquired intangibles, costs incurred in connection with a restructuring program or other organizational transformation activities planned and controlled by management, or cost related mainly to advisory fees, integration, separation, carve-out costs, earn-out credits or charges and regulatory changes requiring retrospective application which may result in one-off impact to the Income Statement and adjustments made to reflect the associated tax charge relating to the above items.
Regulatory driven changes qualify only where:
- The change is externally imposed (law or regulation)
- Requires retrospective application, and
- Results in a non-recurring adjustment
Below are the accounting elements not included in the FY-26 non-IFRS guidance, which remain unchanged
- FY-26 estimated share-based payments and related social charges of c.4-5% of revenue
- FY-26 estimated amortisation of acquired intangibles of USD 40m
- FY-26 estimated restructuring/M&A related costs of USD 14-15m
Investor and media contacts
| Investors | International media | Swiss media |
| Adam Snyder Corporate Affairs Director, Temenos Email: [email protected] Tel: +44 207 423 3945 | Conor McClafferty FGS Global on behalf of Temenos Email: [email protected] Tel: +44 7920 087 914 | Martin Meier-Pfister IRF on behalf of Temenos Email: [email protected] Tel: +41 43 244 81 40 |